Have you ever heard people talking about blockchain and wondered, “What exactly is it?” You’re not alone.
When I first started learning about cryptocurrency, I kept seeing words like Bitcoin, Ethereum, and blockchain, but no one explained what blockchain actually was in simple terms.
The truth is, blockchain isn’t as complicated as it sounds. It’s simply a secure digital record that stores information and transactions without being controlled by a single bank, company, or government.
Once you understand this one concept, everything else, from Bitcoin and Ethereum to smart contracts, DeFi, and Web3, starts to make much more sense.
So now I’ll explain what blockchain is, how it works, its key components, the different types of blockchains, and why it’s one of the most important technologies behind cryptocurrency.
What Is A Blockchain?
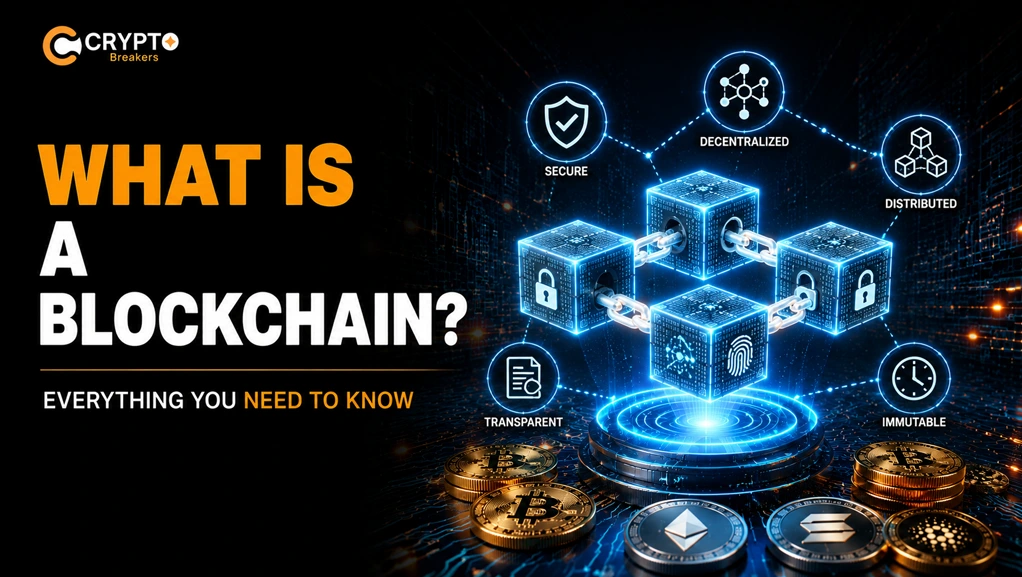
A blockchain is a decentralized digital ledger that securely records transactions across a network of computers instead of relying on a single authority such as a bank, company, or government.
The term blockchain consists of two parts:
- Block: A digital record that stores a group of verified transactions and other data.
- Chain: A sequence of blocks linked together in chronological order using cryptographic hashes.
Each new block is connected to the previous one, creating a continuous chain of records. Once a block is validated and added to the blockchain, altering its data becomes extremely difficult because every connected block and network participant would also need to be changed.
Blockchain technology is best known for powering cryptocurrencies such as Bitcoin and Ethereum, where it enables secure peer-to-peer transactions without intermediaries.
Today, it is also used for smart contracts, decentralized finance (DeFi), digital identity, supply chain management, and other applications that require transparent and tamper-resistant record-keeping.
What Is a Blockchain Ledger?
A blockchain ledger is a digital record that stores every transaction made on a blockchain. Instead of being controlled by a single bank or company, the ledger is shared across many computers (nodes) on the network, so everyone has the same up-to-date copy.
Unlike a traditional ledger, a blockchain ledger has several unique features:
- Distributed: Copies of the ledger are stored on multiple nodes, not on one server.
- Immutable: Once a transaction is confirmed, it cannot be changed or deleted.
- Append-only: New transactions are added as new blocks, while previous records remain the same.
- Cryptographically secured: Each block is connected to the previous one using cryptographic hashes, making the ledger highly secure.
- Transparent: On public blockchains like Bitcoin and Ethereum, anyone can view and verify transactions.
Whenever someone sends Bitcoin, transfers Ethereum, uses a smart contract, or mints an NFT, the transaction is permanently recorded in the blockchain ledger.
Note: Public blockchains let anyone view the ledger, while private and permissioned blockchains only allow approved users to access it.
How Is Blockchain Used in Crypto?
Blockchain is the technology that makes cryptocurrencies work. It records every transaction, verifies ownership, and keeps the network secure without relying on a bank or other central authority.
When you buy, sell, send, or receive cryptocurrency, the network verifies the transaction and permanently records how blocks are added to the chain. This allows users to transfer digital assets directly with each other (peer-to-peer) without intermediaries.
Blockchain also powers many other parts of the crypto ecosystem:
- Cryptocurrency transactions: Records transfers of coins and tokens securely.
- Ownership verification: Confirms who owns digital assets through public and private keys.
- Smart contracts: Automatically execute agreements on blockchains like Ethereum.
- DeFi (Decentralized Finance): Supports lending, borrowing, staking, and decentralized trading.
- NFTs (Non-Fungible Tokens): Store proof of ownership for digital art, collectibles, and other digital assets.
Different cryptocurrencies run on different blockchain networks. Some have their own blockchain, while others are built on an existing one.
| Cryptocurrency | Blockchain Network |
|---|---|
| Bitcoin (BTC) | Bitcoin |
| Ether (ETH) | Ethereum |
| Solana (SOL) | Solana |
| Polygon (POL) | Polygon |
| USDC | Available on multiple blockchains, including Ethereum, Solana, and Polygon |
If you’re tracking these networks and want to stay updated with how their underlying assets are performing right now, the Cryptobreakers live coin price tracker will help you to view real-time market updates and valuations.
Note: If a token is described as being “on Ethereum,” it means its transactions and ownership are recorded on the Ethereum blockchain.
Key Components of a Blockchain
A blockchain is made up of several components that work together to record transactions, verify data, and keep the network secure.
Understanding these building blocks makes it easier to see how cryptocurrencies like Bitcoin and Ethereum operate.
What Is a Blockchain Network?
A blockchain network is a group of computers (nodes) connected to maintain and update the same blockchain ledger. Instead of relying on a central server, every participating node helps verify transactions and keep the network secure.
A blockchain network has several key features:
- Peer-to-peer – Nodes communicate directly without a central authority.
- Distributed – Every participating node stores a copy of the blockchain.
- Consensus-based – New transactions are added only after the network agrees they are valid.
- Public or private – Networks like Bitcoin and Ethereum are public, while private blockchains restrict participation to approved users.
What Is a Blockchain Node?
A blockchain node is a computer connected to a blockchain network. It stores blockchain data, shares information with other nodes, and helps verify transactions.
Common types of blockchain nodes include:
- Full node – Stores the complete blockchain and verifies every transaction independently.
- Light node – Stores only essential data and relies on full nodes for additional information.
- Validator or miner node – Confirms transactions and helps create new blocks, depending on the blockchain’s consensus mechanism.
- Archive node – Keeps the complete blockchain history for explorers, developers, and analytics platforms.
Without nodes, a blockchain network cannot process transactions or remain decentralized.
What Is a Blockchain Transaction?
A blockchain transaction is the transfer of cryptocurrency or digital data from one wallet address to another. Every transaction is verified by the network before it is permanently added to the blockchain.
A typical blockchain transaction follows these steps:
- You create a transaction using your crypto wallet.
- The transaction is broadcast to the blockchain network.
- Network nodes verify the digital signature, wallet balance, and transaction details.
- Verified transactions are grouped into a new block.
- After the block is confirmed, the transaction is permanently recorded on the blockchain.
A blockchain transaction usually includes:
- Sender’s wallet address
- Recipient’s wallet address
- Amount being transferred
- Transaction fee
- Digital signature for authentication
Tip: Always check the recipient’s wallet address before sending cryptocurrency. Once a blockchain transaction is confirmed, it cannot be reversed.
What Is a Nonce in Blockchain?
A nonce is a unique number used once during the mining process to find a valid hash that meets the blockchain’s difficulty requirements.
This is where blockchain gets slightly technical, but it’s simpler than it sounds.
In Proof of Work (PoW) blockchains like Bitcoin, miners compete to solve a mathematical puzzle. The nonce is the variable they keep changing until they find a result (called a hash) that meets the network’s target difficulty.
Here’s how it works:
- A miner takes the block’s data (transactions, previous block hash, timestamp)
- They add a nonce (starting at 0)
- They run everything through a hashing algorithm (SHA-256 for Bitcoin)
- If the resulting hash doesn’t meet the difficulty target, they change the nonce and try again
- This process repeats billions of times per second until a valid hash is found
The miner who finds the correct nonce first gets to add the block and receives the block reward (currently 3.125 BTC as of 2025 after the April 2024 halving).
Note: Nonces are primarily relevant to Proof of Work blockchains. Proof of Stake (PoS) blockchains like Ethereum (post-Merge) use validator selection instead of mining.
What Is a Smart Contract in Blockchain?
A smart contract is a self-executing digital program stored on a blockchain. It automatically performs an action when the conditions written in the contract are met, without needing a bank, lawyer, or other intermediary.
For example, if you buy an NFT using Ethereum, the smart contract automatically transfers ownership of the NFT to your wallet after it receives the required payment. No one has to approve the transaction manually.
Smart contracts are widely used to power:
- DeFi (Decentralized Finance) platforms for lending, borrowing, staking, and trading.
- NFT marketplaces for creating, buying, and selling digital collectibles.
- DAOs (Decentralized Autonomous Organizations) for community voting and governance.
- Token creation and cryptocurrency launches.
- Blockchain games and other Web3 applications.
Ethereum was the first blockchain to popularize smart contracts, but today they are also supported by networks such as BNB Chain, Solana, Polygon, and Avalanche.
Types of Blockchains
Not all blockchains are built for the same purpose. Depending on the use case, networks are designed as public or private blockchains to offer varying levels of access, speed, and security.
Some are open for anyone to use, while others are designed for businesses or organizations that need more control over who can access the network.
1: Public Blockchain
A public blockchain is open to everyone. Anyone can join the network, view transactions, and help validate new blocks without needing permission.
Popular examples include:
- Bitcoin
- Ethereum
- Solana
- BNB Chain
Public blockchains are widely used for cryptocurrencies, smart contracts, DeFi, and NFTs because they are transparent and decentralized.
2: Private Blockchain
A private blockchain is controlled by a single organization. Only approved users can access the network or validate transactions.
Private blockchains are commonly used by businesses for:
- Supply chain management
- Healthcare records
- Financial services
- Enterprise data sharing
Because participation is restricted, private blockchains generally offer faster transaction speeds and greater privacy.
3: Consortium Blockchain
A consortium blockchain is managed by multiple organizations instead of a single company. Each participating organization helps maintain the network and validate transactions.
This type of blockchain is often used in industries where several organizations need to share data securely, such as banking, logistics, and healthcare.
4: Hybrid Blockchain
A hybrid blockchain combines features of both public and private blockchains. Organizations can keep sensitive information private while making selected data publicly accessible when needed.
Hybrid blockchains are commonly used for digital identity systems, government services, and enterprise applications that require both privacy and transparency.
Which Type of Blockchain Is Best?
The right blockchain depends on its intended use:
| Type | Best For |
|---|---|
| Public Blockchain | Cryptocurrencies, DeFi, NFTs, and Web3 applications |
| Private Blockchain | Internal business operations and enterprise data |
| Consortium Blockchain | Collaboration between multiple organizations |
| Hybrid Blockchain | Applications requiring both privacy and public verification |
Why Is Blockchain Technology Important?
Blockchain technology is transforming industries by offering a secure, transparent, and decentralized way to store and share data. However, like any technology, it has both strengths and limitations that are important to understand.
Benefits of Blockchain Technology
- Decentralized – No single bank, company, or government controls the network.
- Transparent – Transactions on public blockchains like Bitcoin and Ethereum can be viewed and verified by anyone.
- Secure – Cryptographic hashing and consensus mechanisms protect data from unauthorized changes.
- Immutable – Once a transaction is confirmed, it cannot be edited or deleted.
- Peer-to-peer transactions – Users can transfer digital assets directly without intermediaries.
- Smart automation – Smart contracts automatically execute transactions when predefined conditions are met.
- Global access – Anyone with an internet connection can participate in a public blockchain network.
- 24/7 availability – Blockchain networks operate continuously without traditional banking hours.
Challenges and Limitations of Blockchain
Despite its advantages, blockchain technology still has several challenges:
- Scalability – Some blockchain networks become slower as transaction volume increases.
- Transaction fees – Network congestion can increase fees, especially on Ethereum.
- Energy consumption – Proof of Work (PoW) blockchains like Bitcoin require significant computing power.
- Learning curve – New users must understand wallets, private keys, and blockchain transactions.
- Irreversible transactions – Confirmed transactions usually cannot be reversed.
- Smart contract risks – Coding errors or vulnerabilities can expose decentralized applications to security issues.
- Regulatory uncertainty – Laws governing blockchain and cryptocurrencies continue to evolve across different countries.
Blockchain Technology: Real-Life Applications
This section is very special for those who think blockchain technology is only limited to cryptocurrencies. We will discuss some other real-life applications that make this technology worthy.
1. Healthcare: In healthcare, blockchain technology is implemented to store sensitive patient information and medical data.
2. Insurance: The insurance industry explores the use of this technology for claims processing, fraud detection, policy management, and smart contracts
3. Gaming: In gaming, blockchain enables secure and transparent item ownership and builds new gaming economies and experiences.
4. Asset management: Many asset managers use blockchain to track and manage assets more effectively and also provide greater transparency to investors.
5. Public sectors: When it comes to land registration, document management, and services related to the public sector, it enhances transparency and security.
6. Cybersecurity: The decentralized nature of blockchain enables protection against cyber threats, reducing the risk of data breaches or hacking.
People Also Ask
Is Blockchain the Same as Bitcoin?
No. Bitcoin is a cryptocurrency that runs on its own blockchain. Blockchain is the underlying technology that Bitcoin and thousands of other cryptocurrencies and applications use.
Who invented blockchain?
In 1991, Haber and Stornetta introduced blockchain to timestamp digital documents. However, in 2008, Satoshi Nakamoto popularized it by using it as a foundation of Bitcoin.
Is Blockchain Only Used for Cryptocurrency?
No. Blockchain is used across industries including supply chain management, healthcare records, digital identity, voting systems, real estate, and intellectual property verification.
Who is the CEO of blockchain?
The CEO of blockchain is Peter Smith. He is the co-founder of blockchain.info, a Bitcoin block explorer and cryptocurrency wallet provider.
Can a Blockchain Be Hacked?
Compromising a major public blockchain like Bitcoin or Ethereum is extremely difficult due to decentralized consensus and cryptographic security. However, individual wallets, smart contracts, and centralized platforms connected to blockchains can be vulnerable.
Is Blockchain Data Really Permanent?
Yes. Once a transaction is confirmed and added to a public blockchain, it becomes part of a permanent, tamper-resistant record. Altering it would require controlling the majority of the network, which is practically impossible on large blockchains.
Does Using Blockchain Cost Money?
Interacting with a blockchain typically involves transaction fees (often called gas fees) paid to validators or miners who process and secure the network. Fees vary depending on network congestion and the blockchain used.
In crypto’s early days, it was not that easy to calculate coin pricing and estimated transaction costs, but now you can easily calculate what a specific amount of crypto is worth in your local currency using CryptoBreakers crypto converter tool.
Who Controls a Blockchain?
Public blockchains like Bitcoin and Ethereum are not controlled by any single entity. They’re maintained by a distributed network of nodes and governed by their respective consensus mechanisms and community governance processes.
My Take: Why Understanding Blockchain Matters
In my opinion, understanding blockchain is one of the best investments you can make before getting into cryptocurrency. You don’t need to learn how to code, but knowing how transactions, wallets, and smart contracts work can help you make smarter decisions and avoid costly mistakes.
The crypto market will continue to evolve, but the fundamentals of blockchain remain the foundation of Bitcoin, Ethereum, DeFi, and the broader Web3 ecosystem. Taking the time to understand them today will give you more confidence as you explore the world of crypto.